

Key Takeaways
- Your premium buys access to a shared pool, not a personal savings account you can draw from freely.
- A deductible is the amount you pay out of pocket before the insurer pays its share.
- Higher deductibles generally mean lower premiums, but more financial exposure per claim.
- Insurers price risk individually; your claims history, location, and coverage type all affect your premium.
- Policy exclusions define what is not covered, and reading them matters as much as reading the benefits.
- A licensed insurance agent or adviser can help match coverage to your specific situation.
Insurance
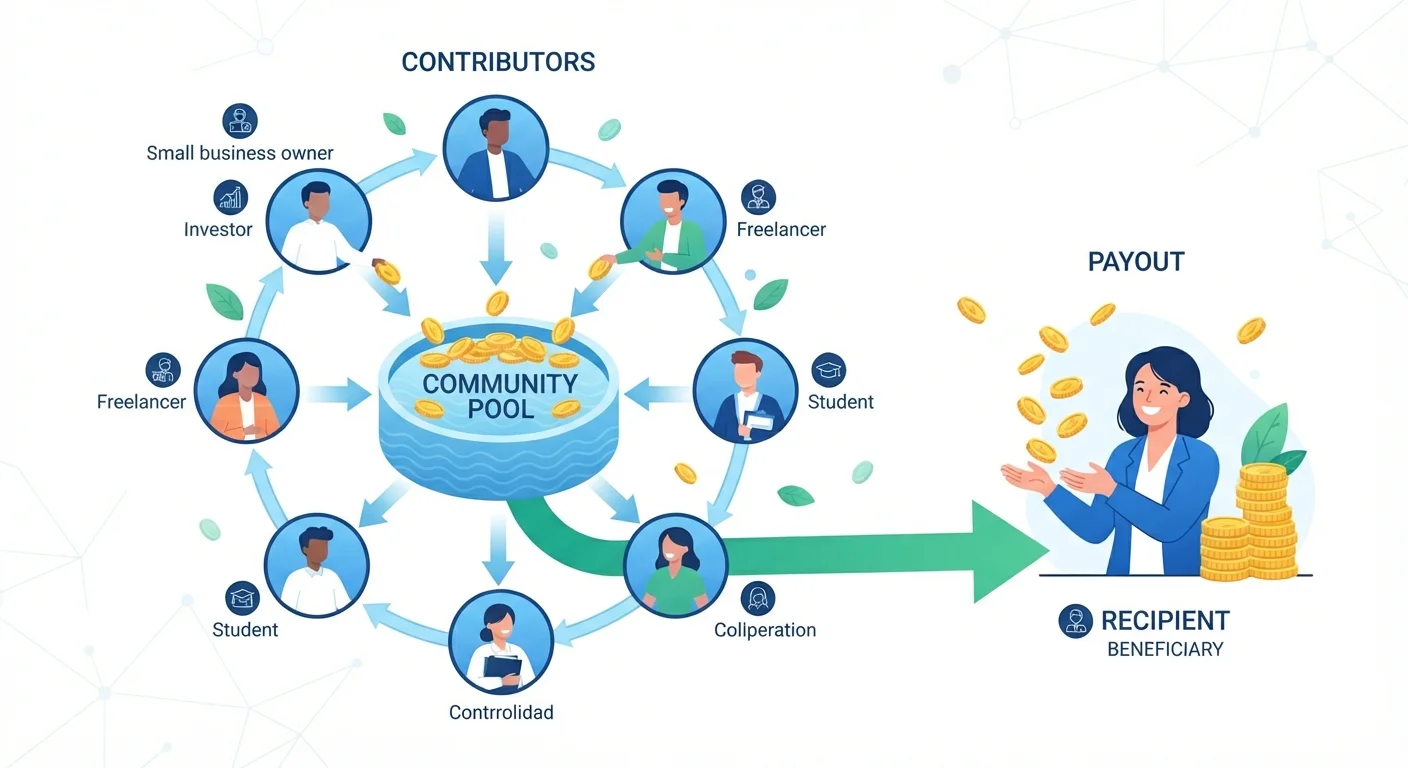
Insurance is a financial arrangement where many people each pay a regular fee (called a premium) into a shared fund. When one of those people suffers a covered loss, the fund pays out to cover some or all of the cost. The logic is straightforward: a loss that would ruin one person is manageable when spread across thousands.
Insurers use actuarial science to estimate the probability and cost of claims across a pool, then set premiums so that total collected premiums cover expected claims plus operating costs and a reserve margin.
The core idea: shared risk
No single person can predict whether their house will catch fire, their car will be totaled, or a medical emergency will cost $80,000. But across a large group of people, those events happen at fairly predictable rates. Insurance is built on that predictability.
An insurer collects premiums from thousands of policyholders and uses that money to pay the relatively small number of people who suffer losses in any given period. Each member of the pool pays a fraction of what a catastrophic loss would cost individually. That is the deal.
This arrangement only works if the pool is large enough and if the insurer prices premiums accurately. Underpriced premiums mean the fund runs short. Overpriced premiums push customers away. Actuaries, who specialize in statistical risk analysis, spend their careers finding that balance.
What your premium actually pays for
Your premium is not deposited into a personal account. It goes into the pool. Think of it like property taxes for a shared road: you pay whether or not you personally hit a pothole that month.
Premiums cover three things: expected claims across the pool, the insurer's operating costs, and a reserve fund for unexpectedly large or frequent losses. A portion also goes toward profit or, for mutual insurers, is returned to policyholders.
Your individual premium depends on how risky you appear to the insurer. Someone in a flood zone pays more for homeowners coverage. A driver with recent accidents pays more for auto coverage. Age, location, health history, and the coverage amount you choose all feed into the calculation. Factors that push premiums higher include both personal behavior and broader market trends outside your control.
~$1.4T
U.S. property and casualty premiums written annually
According to the Insurance Information Institute, U.S. property and casualty insurers collect roughly $1.4 trillion in written premiums each year, illustrating the scale of the shared risk pool.
6 in 10
Americans who say they are underinsured
A 2023 Policygenius survey found that approximately 6 in 10 U.S. adults believe they do not have enough life insurance coverage for their household's needs.
Deductibles, limits, and exclusions
Three policy mechanics determine how much you actually receive after a loss.
The deductible is what you pay first. If a covered repair costs $5,000 and your deductible is $1,000, the insurer pays $4,000. A higher deductible lowers your premium because you absorb more of the first-dollar risk yourself. The trade-off between deductible and premium is one of the most practical decisions you make when selecting a policy.
The policy limit is the maximum the insurer will pay. If your limit is $300,000 and your loss totals $350,000, you cover the remaining $50,000. Choosing a limit that is too low to cover a realistic worst-case loss defeats the purpose of the policy.
The exclusions list what the policy will not cover regardless of circumstances. Standard homeowners policies commonly exclude floods, earthquakes, and pest damage. Reading exclusions is as important as reading the benefits. A full glossary of insurance terms can help you parse policy language you encounter.
How a claim becomes a payout
Filing a claim starts a verification process. You notify the insurer of the loss, document the damage or event, and submit supporting evidence. The insurer assigns an adjuster to confirm the loss is real, covered under your policy, and valued accurately.
Once the adjuster completes their review, the insurer calculates the payment: the covered loss amount minus your deductible, capped at your policy limit. For health insurance, the calculation also factors in coinsurance and copays, which split remaining costs between you and the insurer after your deductible is met.
Disputes can arise over the size of a loss or whether an event is covered. Policyholders have the right to appeal claim decisions, and most states have a department of insurance that handles complaints against insurers.
This article is for general informational purposes only and does not constitute personalized insurance, financial, or legal advice. Coverage terms, exclusions, and regulations vary by provider and state. Consult a licensed insurance agent or adviser for guidance specific to your situation.