
Key Takeaways
- Coverage only applies to reasons explicitly listed in your policy; unlisted reasons are typically excluded.
- Pre-existing medical conditions are often excluded unless you purchase a waiver within a short window of your initial trip deposit.
- Cancel for any reason (CFAR) upgrades broaden cancellation coverage but reimburse only a percentage of trip cost.
- Claims require documentation: receipts, medical records, airline delay notices, and police reports where relevant.
- Reading the exclusions section of a policy is as important as reading what the policy covers.
Travel insurance claim
A travel insurance claim is a formal request you submit to your insurer asking to be reimbursed for a covered loss that occurred during your trip. Common losses include trip cancellations, emergency medical expenses, lost baggage, and travel delays. Whether a claim gets paid depends on the specific terms, exclusions, and documentation requirements written into your policy.
Most travel insurance policies are indemnity contracts, meaning they reimburse actual documented losses up to stated limits rather than paying a fixed benefit. Policies vary significantly by insurer, so always read the Certificate of Insurance, not just the marketing summary.
How travel insurance coverage actually works
Travel insurance is not a blanket safety net. It is a contract that pays for specific losses caused by specific reasons, listed in writing. If your reason for canceling or your type of loss does not appear in the policy's covered perils or covered benefits sections, the insurer has no obligation to pay. That distinction is the single most important thing to understand before buying a policy.
Policies are generally structured around several core coverage categories: trip cancellation, trip interruption, emergency medical and evacuation, baggage loss or delay, and travel delay. Each category has its own limit, its own list of covered causes, and its own exclusions. A policy that covers trip cancellation does not automatically cover trip interruption to the same dollar amount, and neither automatically covers medical expenses abroad.
For a broader foundation on how insurance contracts work, see how insurance actually works, which covers risk pooling, deductibles, and how claims fit into the overall system.
Buy coverage close to your deposit date
The date you pay your first trip deposit, not the date you book flights, starts the clock on pre-existing condition waivers and some other time-sensitive benefits. Buying a policy weeks or months after that initial deposit may close off coverage options that would otherwise have been available.
What travel insurance typically covers
Trip cancellation pays non-refundable, prepaid costs when you cancel before departure for a covered reason. Common covered reasons include sudden illness or injury to you or a traveling companion, the death of an immediate family member, jury duty, a natural disaster that makes your destination uninhabitable, or the financial default of a travel supplier.
Emergency medical coverage pays for treatment when you get sick or injured during the trip. For US travelers, this is particularly relevant internationally, where domestic health insurance often provides little or no coverage. Medical evacuation coverage, sometimes sold separately, pays for transport to an adequate medical facility when local care is insufficient. These costs can reach six figures without insurance.
Baggage loss and delay coverage reimburses you for lost, stolen, or damaged belongings and, in the case of delay, for essential items you buy while waiting for bags to arrive. Travel delay coverage pays for meals and lodging when a covered reason (airline mechanical failure, severe weather) delays your trip beyond a stated number of hours.
Trip planning resources can help you identify which coverage categories matter most for a given destination or trip type.
What gets denied and why
The most common denial reasons fall into predictable categories.
Pre-existing conditions. If you had a medical condition before purchasing the policy, related claims are typically excluded. Most policies define a "look-back period" of 60 to 180 days before purchase; any condition that was treated, symptomatic, or medically documented in that window is considered pre-existing. A waiver is available on many policies if you buy within a specific number of days (often 14 to 21) of your initial trip deposit and are medically fit to travel at purchase.
Change of mind or fear. Not wanting to travel, concerns about civil unrest, or general anxiety about a destination are not covered reasons under standard cancellation policies. A government travel advisory may trigger coverage in some policies, but the advisory level must meet the policy's specific threshold. See how travel advisories work in practice for context on advisory levels.
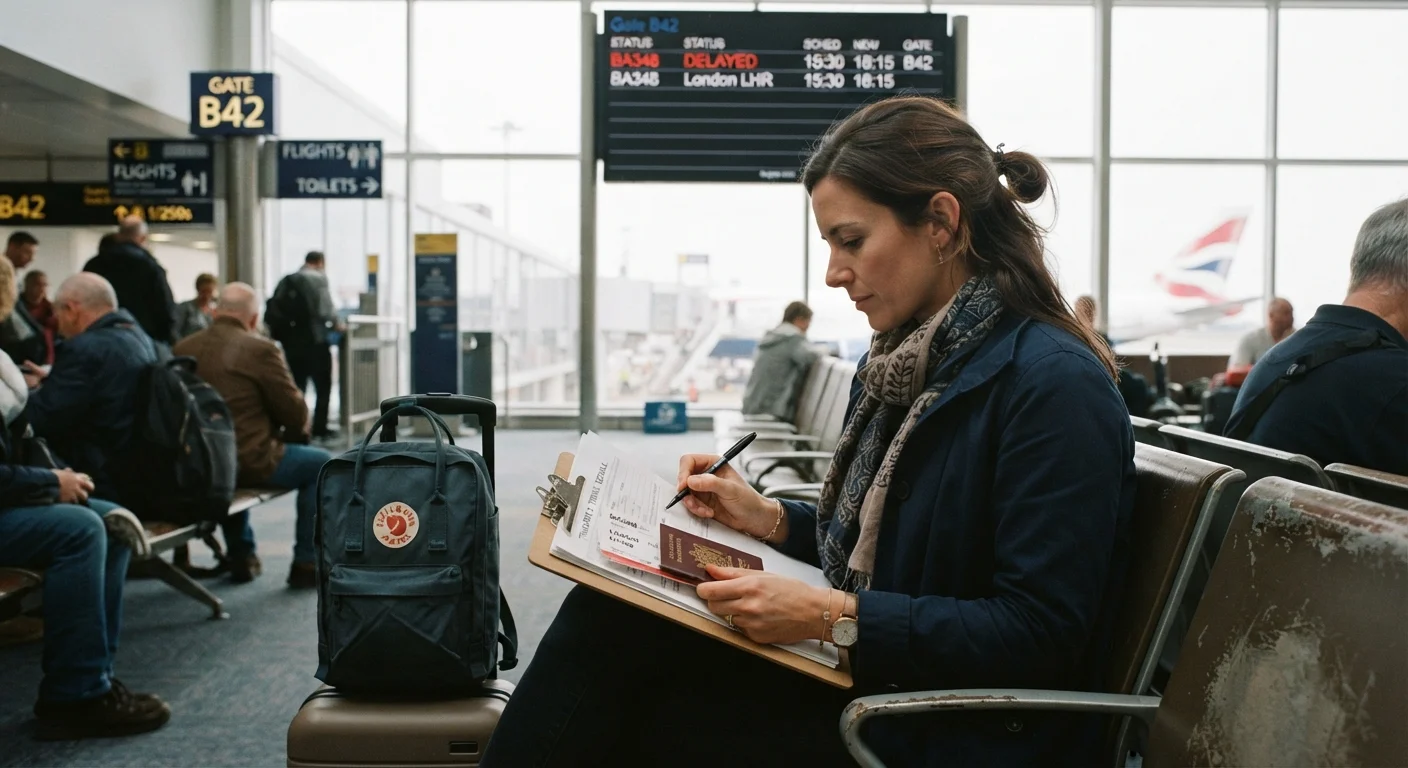
Undocumented losses. Claims without supporting documentation are routinely denied. A medical claim needs physician records. A baggage claim needs an airline property irregularity report and receipts. A delay claim needs written confirmation from the carrier. Collect documentation at the time of the incident, not afterward.
Activities and exclusions. Injuries from activities the policy classifies as hazardous, losses caused by alcohol or drug use, and losses from acts of war are standard exclusions. The exclusions section of any policy is worth reading in full before purchase.
CFAR is an upgrade, not a standard feature
Cancel for any reason coverage is not included in most base travel insurance policies. It is a paid upgrade, typically adds 40 to 50 percent to the policy premium, and reimburses only a portion of non-refundable costs. It also usually requires that you cancel at least 48 to 72 hours before departure. Confirm these details directly with your insurer before assuming CFAR applies.
Filing a claim: what the process involves
Contact your insurer as soon as a covered event occurs. Most policies have notification requirements with firm deadlines. Waiting until you return home to report a medical emergency that happened on day two of your trip can complicate or invalidate a claim.
Keep every piece of paper and every digital confirmation. Itemized receipts, pharmacy records, hotel invoices, airline delay notices, and any correspondence with service providers all support your claim. For theft or loss, file a police report locally and keep a copy.
If a claim is denied, you have the right to appeal. Review the denial letter against the policy language and provide any documentation the insurer says is missing. State insurance commissioners in the US handle complaints when disputes remain unresolved, and travel insurance policies sold in the US are regulated at the state level.
Travel insurance sits within a broader insurance category worth understanding. The same principles that govern coverage decisions in homeowners policies apply here: what you are covered for, up to what limit, and for what causes are defined by the contract, not by expectations.
This article is for general informational purposes only and does not constitute insurance or financial advice. Policy terms, coverage, exclusions, and eligibility vary by insurer and by state. Read your policy documents carefully and consult a licensed insurance professional for guidance specific to your situation.